Why Past Performance Means Nothing
The Myth of “Track Record Investing”
Among even the most hallowed asset management firms, prior success can be attributed not to a series of calculated, informed actions or unique insights but rather the good fortune of being in the right place at the right time–something also known as random luck.
One of the most attractive illusions of investing involves judging a fund’s past success (or “track record”) to be an indication of future success. For the most part, it is only after a fund has performed beyond expectations that any mention of planning or strategy begins to get thrown around. While there are still quite a few experienced, diligent mutual fund managers, past performance is only a very limited and ultimately unreliable measure of success, and no one is above the whims of the stock market. Just like the debunked notion of “market timing”, which we have addressed previously in our ongoing look at popular investing myths, “track record investing” does not hold all of the answers for sound investing.
To be fair, some of the fault with track record evaluation lies not solely with the managers but with the market itself. As we have already established, no one can predict market performance, and the standards for one decade may not apply to another decade and may adversely affect the success rate for even the most accomplished fund managers. However, the speculative if not reckless practices of some stock-based mutual fund managers and firms, which usually stem from the same misguided attempt to time the market that plagues individual investors, only exacerbate the process just for the sake of one individual’s (or group’s) attempt to claim mastery over the market. In fact, when evaluated* alongside the natural, “untouched” progress of a market index like the S&P 500, actively-managed mutual funds actually underperform on average. Moreover, fund managers who excelled for one stretch of a few years routinely failed to repeat the same level of success in subsequent years. That means that for every compelling story about past glories, there is at least one less-than-ideal episode to balance it out.
Even a fund that has a sterling history of success will not yield commensurate gains for everyone who invests in the future. When evaluating the merit of any mutual fund, it is crucial to take into account a range of factors that will directly impact your finances, including any associated fees and costs, tax implications, and whether or not the performance record available to you contains the full and complete history of returns from that fund and any funds that have rolled into it. Additionally, a fund that has performed well over time has not necessarily performed well consistently or maintained stability; one attribute that can be gauged with some accuracy by assessing past performance is a fund’s volatility, and this cannot be overlooked, regardless of any other merits the fund may possess.
The next time asset managers next try to entice you with promises of conquering the new decade using the same insights that have “always” produced returns in the past, you can be confident in your decision to ask for more information and press for some explanation as to how their management can actually benefit you. Approach your investing with the confidence to hold fund managers and firms to the standards they claim they deserve, and do not be afraid to ask for as much information as possible. There is no such thing as being too well-informed when it comes to your finances.
Episode 164 of the Your Business Your Wealth podcast, “Does 20/20 Hindsight Help?”, contains more valuable information regarding the fallacy of track record investing and is available now on our official YouTube channel and website. Subscribe to our podcast to learn more about the best practices for investing and securing your family’s financial future, and avoid the pitfalls of the dreaded Illusions of Investing.
*The 30 top mutual fund managers from 2008-2012, when evaluated over the next 5 years, charted returns of 4.99%. In the same timeframe, the S&P 500 returned 16.25%, a disparity of 226%, while the average U.S. equity fund registered 12.8% on returns, a disparity of 157%.
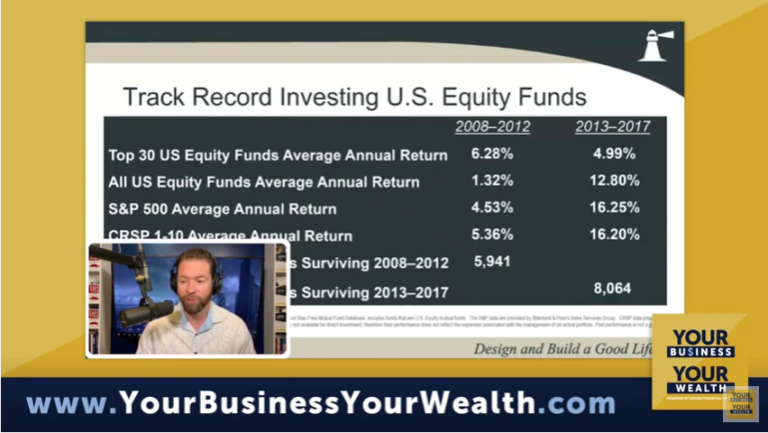
Mutual fund data provided by CRSP Survivor Bias Free Mutual Fund Database, includes funds that are U.S. Equity mutual funds. The S&P data are provided by Standard & Poor’s Index Services Group. CRSP data provided by the Center for Research in Security Prices, University of Chicago. Indices are not available for direct investment, therefore their performance does not reflect the expenses associated with the management of an actual portfolio. Past performance is not a guarantee of future results. Not actual investor results