PODCAST EPISODE 369 – Why Your Losses May Not Cancel Out Your Win
PODCAST EPISODE 369 – Why Your Losses May Not Cancel Out Your Win
An episode of More Than Commas featuring Trent Trailov, CPA and founder of Trail CPA, on why gambling wins and losses do not always cancel out on your tax return, and how good records, tax planning, and clear limits can help protect your financial future.
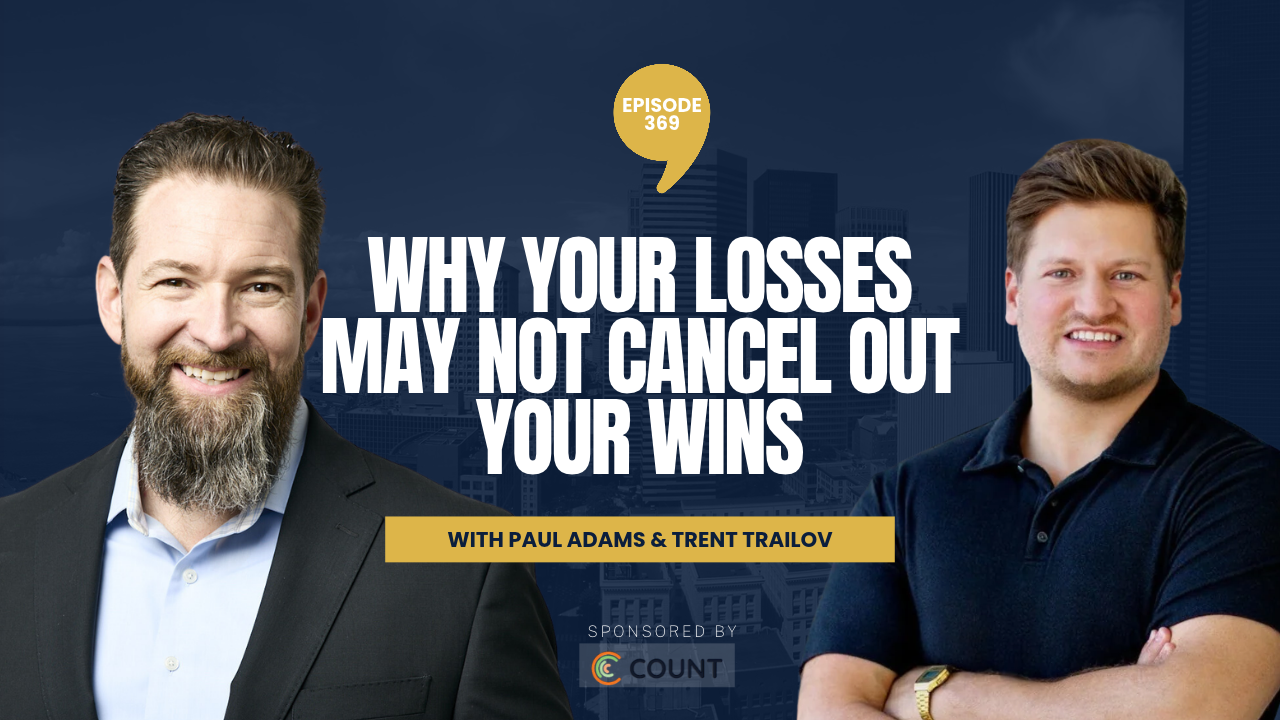



A $15,000 win sounds like a good night. But what if you already lost $15,000 before that payout? That was the example I brought to Trent Trailov in this episode of More Than Commas. His answer surprised me: walking out even does not necessarily mean you are even after taxes.
That was the question I wanted to explore with Trent Trailov, CPA and founder of Trail CPA, for this episode of More Than Commas. Trent and I have done financial education together over the years, and this is a topic his team has been seeing more often as online gambling and prediction markets have become more accessible.
Whether you occasionally visit a casino, play poker, or use an online platform, it is worth understanding the tax consequences before spending a win or assuming a loss cancels it out.
Key Takeaways:
- Gambling winnings generally must be reported even when you do not receive a Form W-2G. A reporting threshold is not a tax-free allowance.
- For recreational gamblers, deducting losses generally requires itemizing and keeping supporting records. Losses do not automatically cancel winnings dollar for dollar on a tax return.
- Federal and state rules can produce different results. Where you gamble can matter, even if you live somewhere without a state income tax.
- Good records and a plan for withholding or estimated payments can help you avoid an unwelcome surprise after the money has been spent.
- Gambling should remain recreation, not something you rely on to support your family’s financial future. Talk with your CPA before making assumptions about deductions or business treatment.

A Tax Form Is a Signal, Not the Start of Your Responsibility
I remember living in Las Vegas and seeing what happens when someone wins enough at a slot machine that an employee needs their identification before completing the payout. That is often the moment the tax conversation becomes real.
Trent explained that certain winnings result in a Form W-2G. The payer sends a copy to the winner and to the IRS. Leaving that form off your return can lead to a notice asking about the missing income.
But there is an important distinction: receiving a form and having taxable winnings are not the same question. As the IRS explains, gambling winnings generally must be reported even when they are not reported on a W-2G. The reporting and withholding rules vary by activity and tax year.
Keep track of the activity, not just the forms that arrive in the mail. Your CPA needs the full picture to help you report it correctly.
Why Breaking Even May Not Mean Breaking Even After Taxes
During our conversation, I asked Trent to walk through a hypothetical situation: someone loses $15,000 playing roulette, then hits a $15,000 slot-machine payout.
From that person’s perspective, the big win might feel like getting back what they lost. But the tax return does not necessarily treat those amounts as a simple wash.
For a recreational gambler, losses are generally claimed as an itemized deduction rather than automatically subtracted from winnings. If you take the standard deduction, those losses do not become a separate deduction on top of it. Even when you itemize, applicable limits can prevent a full offset.
Trent put the problem plainly:
“You could find yourself in a scenario where you’re paying tax, but you actually didn’t win any money.”
Trent Trailov
The dollar amounts in our conversation are hypothetical. They are not a calculation of what a particular listener would owe, and the result depends on the facts and applicable law.
State Taxes Can Add Another Layer
Another part of this conversation that caught my attention was geography. Living in a state without a personal income tax does not necessarily mean a win elsewhere comes without a state tax obligation.
Depending on the state and the amount and type of income, you may need to file a nonresident return. A state may also treat losses differently from the federal government.
This is one reason a record of where and when you gambled matters alongside the dollar amounts. If you traveled for a tournament or visited casinos in several states, tell your CPA. Do not assume every state will treat the same activity the same way.
Keep the Records Before You Need Them
Trent described people reaching out after a significant win, only to discover that they had not kept useful records of the losses that came before it.
Keeping even a simple log gives you a starting point. Supporting records can help your CPA understand what happened.
In the episode, we discussed several sources of documentation:
- A contemporaneous log of the dates, locations, activities, winnings, and losses.
- Receipts, tickets, and other supporting records.
- Bank statements and relevant transaction records.
- Casino player-account statements and available online-platform activity reports.
- Forms W-2G and records of any taxes already withheld.
These are supporting materials, not a guarantee that a particular loss will be deductible. An ATM withdrawal alone does not establish what you lost. Ask your tax professional what documentation is appropriate for your activity and keep the underlying records together.
Withholding Is a Payment Toward the Bill, Not the Final Answer
A payout can arrive with some tax already withheld. That does not necessarily mean the final tax obligation has been covered.
Your result depends on your other income, filing status, the applicable tax year, state obligations, and other circumstances. A withholding percentage is not the same thing as your final effective tax rate.
Rather than treating the entire payout as spending money, contact your CPA and ask what should be reserved and whether additional withholding or estimated payments are appropriate. Also confirm how federal and state payments should be handled; a payment to one does not automatically settle the other.
Plan for the tax bill while the payout is still available. Ask your CPA what to set aside rather than assuming the amount withheld will cover everything you owe.
Prediction Markets and Business Treatment Deserve Their Own Conversation
We also discussed prediction markets such as Kalshi and the distinction between recreational gambling and an activity that genuinely qualifies as a trade or business.
Neither is something to settle based on a platform’s marketing language or by forming an LLC after a big win. The applicable tax treatment requires an assessment of the activity, the facts, and current law.
Business status is not an automatic escape from gambling-related deduction limits. Nor does creating an entity automatically make travel, training, or other expenses deductible. If you believe your activity may qualify as a business, get professional guidance before relying on that treatment.
Ask your CPA about business treatment before relying on it, rather than trying to reclassify a year’s activity after a big win.
Keep Recreation From Becoming a Risk to Your Family
I shared with Trent how I have thought about occasional gambling: a limited amount of money spent on recreation, rather than an expectation of earning an income.
That distinction matters far beyond the tax return. Time, stress, and the effect on your household belong in the decision, too. Casino games generally favor the operator over time, although the advantage varies by game and wagering structure.
Trent and I agreed that gambling should not put your financial future, or your family’s financial future, at risk. A possible deduction is not a reason to gamble, and a good night does not make the risks disappear.
Before year-end, get on your CPA’s calendar. You do not want to find out next year that there was something you could have done while there was still time.
Where to go from here
- Want to talk about how a financial decision fits your broader plan? Get in touch with Sound Financial Group.
- Have questions about the tax treatment of your own activity? Visit Trail CPA to learn more or find its introductory-call scheduling link.
- Want the IRS’s overview of reporting and recordkeeping? Read Gambling Income and Losses, and ask your CPA about the rules for your specific tax year.
Get the planning session in early, while you still have time to act. Then get back to living a great life.
Episode disclosures
Gambling winnings are generally subject to federal income tax regardless of whether Form W-2G is issued. Reporting thresholds and withholding requirements vary by gambling activity and tax year. This information is provided for educational purposes only and should not be considered individualized tax advice. Consult a qualified tax professional regarding your specific circumstances.
References to third-party professionals are provided for informational purposes only and do not constitute a guarantee of their qualifications, services, or results. Individuals should independently evaluate any professional before engaging their services. Any material referral arrangements or other conflicts of interest will be disclosed as applicable.
Sound Financial Group and Trail CPA maintain a professional referral relationship and may refer clients to one another when appropriate. No compensation is exchanged for these referrals. This relationship may create a conflict of interest because either firm may have an incentive to recommend the other’s services. Clients are not obligated to engage either firm as a result of a referral.
Casino games generally favor the operator over time, although the house advantage varies by game and wagering structure. Gambling involves financial risk, and losses may exceed winnings.
Tax treatment of gambling winnings, losses, and related expenses depends on individual circumstances and applicable tax laws. Establishing an LLC or sole proprietorship does not automatically qualify gambling activities as a trade or business or make related expenses deductible. Gambling losses and expenses may be subject to limitations. Consult a qualified tax professional regarding your specific situation.
Gambling laws and regulations vary by state and type of activity, including online gambling. Participation in gambling activities may be subject to restrictions based on an individual’s physical location and other applicable legal requirements. This information is for educational purposes only and does not constitute legal or tax advice. Individuals should consult qualified professionals regarding their specific circumstances.
Federal income tax brackets and withholding requirements vary based on tax year, filing status, taxable income, and individual circumstances. Marginal tax rates do not necessarily represent an individual’s effective tax rate or appropriate withholding percentage. This information is for educational purposes only and should not be considered individualized tax advice. Consult a qualified tax professional regarding your specific situation.
By providing this material, we are not providing investment advice tailored to any specific individual or situation, and the distribution of this material alone does not create an advisory or fiduciary relationship. Please contact one of our financial professionals for guidance and information specific to your individual situation. Sound Financial Inc. dba Sound Financial Group is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance. Insurance products and services are offered and sold through Sound Financial Inc. dba Sound Financial Group and individually licensed and appointed agents in all appropriate jurisdictions. This podcast is meant for general informational purposes and is not to be construed as tax, legal, or investment advice. You should consult a financial professional regarding your individual situation. Guest speakers are not affiliated with Sound Financial Inc. dba Sound Financial Group unless otherwise stated, and their opinions are their own. Opinions, estimates, forecasts, and statements of financial market trends are based on current market conditions and are subject to change without notice. Past performance is not a guarantee of future results.